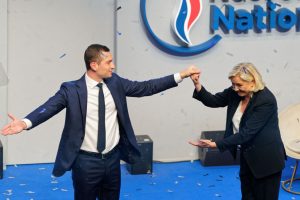
Marine Le Pen has set out the budget she would pursue if elected president, using the National Rally (RN) headquarters on October 6 to raise the party’s net savings target and promise to restore a primary balance within 18 months.
With polls in late September putting her ahead in both rounds of the presidential election on April 18 and May 2, 2027, the presentation was the clearest account yet of how the favourite would tackle a debt burden that markets have begun to treat as a peripheral-country problem.
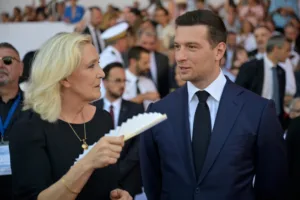
RN president Jordan Bardella, standing beside Le Pen, emphasised that “another budgetary path is possible”.
According to Bardella, the RN plan would improve the public balance by €72 billion, allowing state revenues to cover spending excluding debt servicing. “France would stop accumulating debt,” he said, warning of a “snowball effect” as the cost of servicing the debt is expected to reach €91 billion.
Tax measures include scrapping several production taxes, cutting value added tax (VAT) on energy, applying a 0 per cent VAT rate to 100 essential products, and exempting under-30s earning up to four times the minimum wage from income tax.
“Reduce spending to be able to reduce taxes,” Bardella said, arguing that the plan would give businesses more room to produce and workers more of the fruits of their labour.
Le Pen said the adjustment required had been raised from the €125 billion previously promised to “€140 billion net of savings in 2032 compared with 2026”.
Most of the €140 billion, she said, would come in the first three years through “streamlining the way the government functions”.
She blamed higher interest rates and what she called the “indigent” budget of Prime Minister Sébastien Lecornu and President Emmanuel Macron, and said she hoped not to have to raise the figure again before the second round on May 2, 2027.
The cure, she insisted, would be “redress, not austerity”.
“The policy I will pursue will restore a primary balance in 18 months, then reach a public deficit below 3 per cent in 2030,” she said.
By the end of a term in 2032, she promised a deficit below 2.5 per cent and debt at 112 per cent of GDP, against official forecasts of 5.4 per cent and 119 per cent in 2026.
Public spending would be brought “below 50 per cent of GDP”, from more than 57 per cent now.
The deficit was 5.1 per cent in 2025, with debt at 115.6 per cent of GDP, according to national statistics office Insee.
France’s current government expects to borrow a record €340 billion in 2027, around €28 billion more than in 2026, and still aims to bring the deficit below the EU**’s 3 per cent** ceiling only in 2029.
The RN also wants a binding fiscal rule requiring France to reduce its deficit every year. Le Pen said this would be put to a referendum under Article 11 and written into the Constitution.
The rule would not impose an arbitrary deficit cap. Instead, it would link the maximum deficit to the level at which France’s debt is stabilised.
“I propose to the French that we authorise only a public deficit below the threshold that stabilises the French debt, so that our country gradually frees itself from this dead weight,” she said.
While debt remains above 60 per cent of GDP, the ceiling would sit “at least 0.5 of a point below” that stabilising rate.
A flat 1 per cent limit, she said, “would have had the merit of simplicity but would have been a choice of pure political communication, without any economic or financial sense”.
Alongside the spending cuts, Le Pen promised tax reductions of “at least €30 billion net”, including €20 billion in cuts to production taxes, and an end to what she called the “parallel administrative millefeuille“, a reference to the layering of French public bodies.
Pensions remain the most difficult part of the equation. The RN still wants to reverse the retirement age increase to 64 and return it to 62, or even 60 in some cases.
Le Pen said “corrections” to “unjust or ineffective” measures would yield €15 billion to €20 billion, enough to finance the party’s reform and cut “the deficit left by Emmanuel Macron”.
She also confirmed “a great reform of individual and collective capitalisation” and “a genuine capitalisation pillar”, with details to follow “in the weeks ahead”.
Le Pen repeated that France’s contribution to the EU budget should fall and called on the European Central Bank to “ease the burden” of interest rates.
Le Pen said France’s net contribution to the EU budget should be brought down to €5 billion, from nearly €29 billion planned for 2026.
Politico separately reported that the RN’s counter-budget envisages cutting €19.5 billion from EU contributions, including an €11.1 billion reduction as early as 2027.
“If the French do not choose a political break, France is heading for default,” she said, accusing Macron’s governments of failing to stop “the noose of interest payments from strangling France”.
She lamented that French productivity had “completely fallen behind that of the United States” and that research spending had given France no edge in “the technological battle”.
The line-by-line cuts were not published.
On education, another issue that has brought thousands onto the streets, Le Pen said the RN would maintain a fixed budget despite a declining population. This would create room for more teachers and higher salaries, she said.
She added that improving security and restoring “serenity” in schools would benefit educators.
Bruno Le Maire, finance minister for seven years under Macron until September 2024, dismissed the proposed fiscal rule as “the fig leaf of every politician who does not want to tell the French where the savings will be made, and when”.
Quoting Shakespeare’s Hamlet, “words, words, words”, he called the pledge a scam.
BFM Business made the same point after the event, headlining that Le Pen “remains very vague on the concrete savings”.
French borrowing costs have risen in recent days to levels not seen since 2002, the 10-year OAT breaking above 4.5 per cent on October 1, as investors sell French assets over the deficit and uncertainty surrounding the 2027 election.
Le Pen has sought fiscal credibility with the higher savings figure, but has so far struggled to convince business leaders worried by her euroscepticism and by her plan to reverse the 2023 pension reform while promising €15 billion to €20 billion in pension savings.
Lecornu’s own 2027 budget, presented on October 1 to calm the same markets, claims €43 billion in new savings within a total consolidation effort of €54 billion, and targets a deficit of 5 per cent next year. Its fate in a hung parliament depends partly on the RN, the largest opposition group.